
Bettingbladet releases H1 2026 report on the Swedish online gambling market
Sep 14, 2026
New report maps operator GGR, game supplier market shares, sportsbook technology, payment methods, RTP levels and bonus trends across Sweden's regulated online gambling market in H1 2026.
STOCKHOLM - Sept. 14, 2026 - PRLog -- Bettingbladet has released its Swedish Online Gambling Market Report H1 2026 (the report can be downloaded via this link in English and Swedish), providing a data-driven overview of the companies, suppliers and trends shaping Sweden's regulated online gambling industry.
One of the report's central features is an operator-by-operator analysis of Gross Gaming Revenue (GGR). Beyond operator performance, the report examines slot and live casino supplier market shares, Sweden's most-played games, sportsbook technology providers, RTP levels, payment methods and welcome bonuses.
The report combines public data with Bettingbladet's own research, operator and supplier data and analysis of the Swedish market. Where complete data is unavailable, market shares and certain other figures are estimates and should be interpreted as indicative rather than exact.
Operator GGR reveals major differences in H1 performance
Bettingbladet's GGR analysis reveals significant differences in performance across Sweden's licensed operators during the first half of 2026.
Nordplay Group was among the strongest growers, with Klirr increasing its monthly GGR by approximately 31% between January and June. Newer sister brands Onerush and Jubla increased their GGR by approximately 80% and 16% respectively over the same period.
LeoVegas Group also recorded growth, moving from €16.51 million in GGR in January to €19.42 million in June.
Cherry recorded a stronger second quarter, with 24% higher GGR during April–June compared with the first quarter. Meanwhile, Unibet finished the half strongly, with GGR in June 41% higher than in January, although the report notes that the FIFA World Cup and stronger sports margins likely contributed to the June result.
Pragmatic Play and Play'n GO dominate Swedish slots
The report estimates Pragmatic Play to be Sweden's largest slot supplier with 21.9% of total online slot turnover, narrowly ahead of Swedish-founded Play'n GO at 21.1%.
Hacksaw Gaming has also established a significant position, accounting for an estimated 10.9% of Swedish slot turnover.
At game level, Book of Dead topped Bettingbladet's H1 dataset, while classics such as Starburst, Legacy of Dead and Fire Joker remained among the ten most-played titles alongside newer releases including Pirots 4 and Gates of Olympus 1000.
Evolution controls an estimated 77% of live casino
The live casino market is considerably more concentrated.
Bettingbladet estimates that Evolution accounts for approximately 77% of Swedish live casino turnover, while Pragmatic Play holds an estimated 12.5% market share. Other live casino suppliers combined account for approximately 10.5%.
Evolution's Crazy Time stands out as the clear market leader and is estimated to generate around 10% of Evolution's Swedish live casino turnover on its own.
RTP varies between Swedish operators
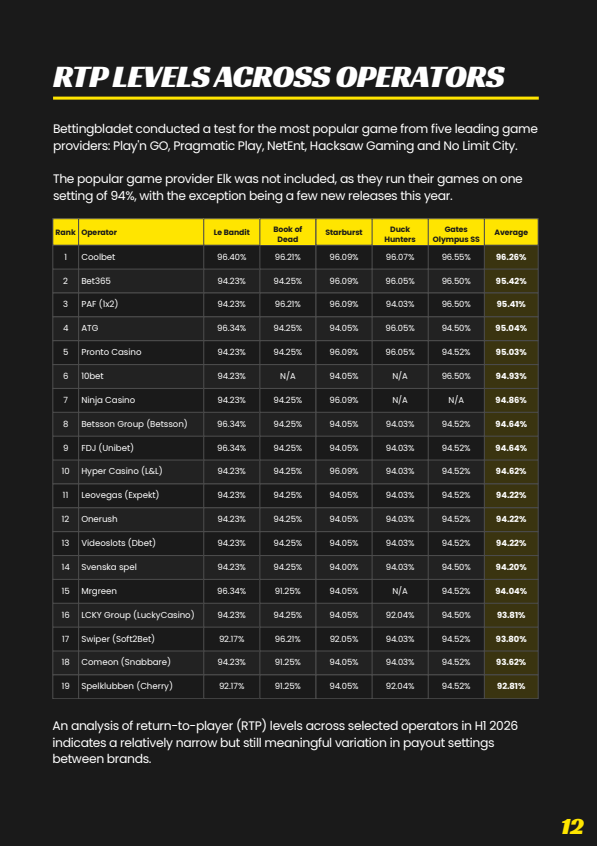
Bettingbladet also compared the RTP settings offered by Swedish operators for selected popular games from five major suppliers.
Across the sample, average RTP ranged from approximately 93.8% to 96.3% depending on the operator, meaning that the same underlying slot can offer different theoretical returns depending on where it is played.
Coolbet recorded the highest average in the study at 96.26%, while ATG, bet365 and PAF all averaged above 95% across the selected games.
The findings indicate that RTP remains another way for operators to differentiate themselves in a Swedish market where promotional opportunities are heavily restricted.
Kambi and Altenar lead sportsbook technology
Bettingbladet found that 51.85% of Swedish operators use either Kambi or Altenar, making the two suppliers the clear leaders by operator count.
However, the picture changes when looking at betting turnover. Kambi remains the dominant supplier by volume, powering sportsbooks for several of Sweden's largest operators, including ATG, Svenska Spel, Unibet and PAF.
Swish and Trustly dominate Swedish gambling payments
The report analysed payment methods across 85 active licensed operators, finding an exceptionally concentrated market for bank-based payments.
Swish was available at 82 of 85 brands (96.5%), while Trustly was offered by 77 (90.6%). Visa was available at 47% of operators, Mastercard at 42%, Zimpler at 28% and Apple Pay at approximately 25%.
A third of the operators analysed offered only two of the 11 payment methods included in the study – typically Swish and Trustly – while just ten brands offered seven or more.
Swedish channelisation remains a challenge
The latest figures cited in the report put overall channelisation at 84%, compared with 86% in 2023 and 85% in 2024. The difference between gambling verticals is particularly notable, with channelisation estimated at 96% for sports betting but only 81% for online casino.
Sweden's regulated online gambling market is estimated to be worth approximately €2.5 billion annually, with operators paying 22% tax on GGR.
About Bettingbladet
Bettingbladet is a gambling industry news site covering online casino, sports betting and developments across the Nordic gambling markets, with Sweden as its primary focus.
Its editorial coverage includes industry news, market analysis, operator and game comparisons, regulatory developments and original studies based on data collected from the Swedish and wider Nordic online gambling markets.
Photos: (Click photo to enlarge)




Source: Bettingbladet
Read Full Story - Bettingbladet releases H1 2026 report on the Swedish online gambling market | More news from this source
Press release distribution by PRLog
STOCKHOLM - Sept. 14, 2026 - PRLog -- Bettingbladet has released its Swedish Online Gambling Market Report H1 2026 (the report can be downloaded via this link in English and Swedish), providing a data-driven overview of the companies, suppliers and trends shaping Sweden's regulated online gambling industry.
One of the report's central features is an operator-by-operator analysis of Gross Gaming Revenue (GGR). Beyond operator performance, the report examines slot and live casino supplier market shares, Sweden's most-played games, sportsbook technology providers, RTP levels, payment methods and welcome bonuses.
The report combines public data with Bettingbladet's own research, operator and supplier data and analysis of the Swedish market. Where complete data is unavailable, market shares and certain other figures are estimates and should be interpreted as indicative rather than exact.
Operator GGR reveals major differences in H1 performance
Bettingbladet's GGR analysis reveals significant differences in performance across Sweden's licensed operators during the first half of 2026.
Nordplay Group was among the strongest growers, with Klirr increasing its monthly GGR by approximately 31% between January and June. Newer sister brands Onerush and Jubla increased their GGR by approximately 80% and 16% respectively over the same period.
LeoVegas Group also recorded growth, moving from €16.51 million in GGR in January to €19.42 million in June.
Cherry recorded a stronger second quarter, with 24% higher GGR during April–June compared with the first quarter. Meanwhile, Unibet finished the half strongly, with GGR in June 41% higher than in January, although the report notes that the FIFA World Cup and stronger sports margins likely contributed to the June result.
Pragmatic Play and Play'n GO dominate Swedish slots
The report estimates Pragmatic Play to be Sweden's largest slot supplier with 21.9% of total online slot turnover, narrowly ahead of Swedish-founded Play'n GO at 21.1%.
Hacksaw Gaming has also established a significant position, accounting for an estimated 10.9% of Swedish slot turnover.
At game level, Book of Dead topped Bettingbladet's H1 dataset, while classics such as Starburst, Legacy of Dead and Fire Joker remained among the ten most-played titles alongside newer releases including Pirots 4 and Gates of Olympus 1000.
Evolution controls an estimated 77% of live casino
The live casino market is considerably more concentrated.
Bettingbladet estimates that Evolution accounts for approximately 77% of Swedish live casino turnover, while Pragmatic Play holds an estimated 12.5% market share. Other live casino suppliers combined account for approximately 10.5%.
Evolution's Crazy Time stands out as the clear market leader and is estimated to generate around 10% of Evolution's Swedish live casino turnover on its own.
RTP varies between Swedish operators
Bettingbladet also compared the RTP settings offered by Swedish operators for selected popular games from five major suppliers.
Across the sample, average RTP ranged from approximately 93.8% to 96.3% depending on the operator, meaning that the same underlying slot can offer different theoretical returns depending on where it is played.
Coolbet recorded the highest average in the study at 96.26%, while ATG, bet365 and PAF all averaged above 95% across the selected games.
The findings indicate that RTP remains another way for operators to differentiate themselves in a Swedish market where promotional opportunities are heavily restricted.
Kambi and Altenar lead sportsbook technology
Bettingbladet found that 51.85% of Swedish operators use either Kambi or Altenar, making the two suppliers the clear leaders by operator count.
However, the picture changes when looking at betting turnover. Kambi remains the dominant supplier by volume, powering sportsbooks for several of Sweden's largest operators, including ATG, Svenska Spel, Unibet and PAF.
Swish and Trustly dominate Swedish gambling payments
The report analysed payment methods across 85 active licensed operators, finding an exceptionally concentrated market for bank-based payments.
Swish was available at 82 of 85 brands (96.5%), while Trustly was offered by 77 (90.6%). Visa was available at 47% of operators, Mastercard at 42%, Zimpler at 28% and Apple Pay at approximately 25%.
A third of the operators analysed offered only two of the 11 payment methods included in the study – typically Swish and Trustly – while just ten brands offered seven or more.
Swedish channelisation remains a challenge
The latest figures cited in the report put overall channelisation at 84%, compared with 86% in 2023 and 85% in 2024. The difference between gambling verticals is particularly notable, with channelisation estimated at 96% for sports betting but only 81% for online casino.
Sweden's regulated online gambling market is estimated to be worth approximately €2.5 billion annually, with operators paying 22% tax on GGR.
About Bettingbladet
Bettingbladet is a gambling industry news site covering online casino, sports betting and developments across the Nordic gambling markets, with Sweden as its primary focus.
Its editorial coverage includes industry news, market analysis, operator and game comparisons, regulatory developments and original studies based on data collected from the Swedish and wider Nordic online gambling markets.
Photos: (Click photo to enlarge)
Source: Bettingbladet
Read Full Story - Bettingbladet releases H1 2026 report on the Swedish online gambling market | More news from this source
Press release distribution by PRLog
More News




YOUR NEWS, OUR NETWORK.
Do you have Great News you want to tell the world?
Be it updates about your business or your community, you can make sure that it’s heard by submitting your story to our network reaching hundreds of news sites across 6 verticals.